
After severe weather hits a commercial building in Bismarck, ND, the owner usually faces two questions at once: what happened to the roof, and what the insurance policy will do about it. The practical decision is what to document, who to contact, and when to arrange a professional roof assessment. This guide explains how storm damage, policy terms, and the claim process fit together. It is general information, not insurance or legal advice, and your policy and insurer decide coverage.
Eagle Eye Roofing Systems provides commercial roofing for Bismarck buildings. To arrange a roof assessment after a storm, call (701) 202-7280.
Common Types of Roof Storm Damage
Commercial roofs can be damaged by storms in several ways:
- Wind: lifted or torn membrane, loosened edges, and displaced flashing or metal panels.
- Hail: punctures, bruising, or surface damage to membranes and coatings.
- Heavy rain: leaks and water entering through damaged seams or flashing.
- Debris: impact from tree limbs or windblown objects.
- Snow and ice: added weight, blocked drains, and ice at roof edges.
Some roof damage is not visible from the ground. Water can enter at one point and show up as a ceiling stain somewhere else, so a visible mark inside is a reason to investigate, not a diagnosis.
Understanding Your Commercial Insurance Policy
Commercial property policies differ, so read yours or ask your agent about the terms that affect a roof claim:
- Whether the roof is covered at replacement cost or actual cash value, and how roof age affects payment
- Deductibles for wind, hail, or other storm events, which may differ from other claims
- Any endorsements or exclusions for wind, hail, or water damage
- Limits on repair versus replacement
- Reporting deadlines and what the policy requires you to do after damage
Coverage decisions come from the policy and the insurer, not from the roofing contractor.
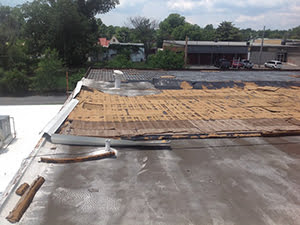
Documenting Commercial Roof Damage
Clear records make it easier to explain what changed and when. Useful steps include:
- Photograph and record damage from safe locations, including interior leaks and ceilings, without climbing onto a wet or snow-covered roof.
- Write down the date of the storm and when you first noticed the damage.
- Take reasonable steps to prevent further damage, such as catching water or moving inventory, and keep receipts.
- Keep a log of communications with your insurer and contractors.
- Arrange a professional roof assessment so the roof is examined by people with proper safety equipment.
What Evidence Can and Cannot Show
Different records answer different questions, and none answers all of them. This table shows what each type of evidence can help establish and where it falls short:
| Evidence | What it can help show | Limits |
|---|---|---|
| Dated photos and video | What was visible, where, and when it was recorded | They document visible conditions but do not establish whether insulation is wet |
| Storm date and weather records | That a storm event occurred on a specific date | They do not prove that a given roof defect came from that storm |
| Roofing contractor’s written assessment | Locations, types, and likely extent of damage, plus the repair scope needed | It documents the roof’s condition; it does not decide coverage |
| Moisture scan or core samples | Whether insulation beneath the membrane is wet | Screening results may require confirmation; direct samples describe only areas tested |
| Earlier inspection and maintenance records | The roof’s condition before the storm and any known earlier problems | They only help if they were made and kept before the damage occurred |
| Written repair estimates | What the repair is expected to involve and cost | Estimates vary with scope, so they should be compared against the same assessment |
Because each item has limits, the strongest file usually combines several. A contractor’s assessment is most useful when it records locations and extent in writing, notes what was not checked, and distinguishes suspected storm-related damage from previously observed wear where the evidence permits.
The Commercial Roof Claim Process
The steps below are typical, but your policy controls the details:
Report the damage. Notify your insurer according to your policy, since policies can set deadlines or notice requirements.
Prepare for the adjuster. The insurer may send an adjuster to inspect the roof. Ask whether your roofing contractor may attend, and bring your photos, records, and any written assessment.
Review the outcome. Read the settlement or decision carefully and compare it with the repair scope in your contractor’s assessment. If you disagree, ask the insurer how re-inspection or disputes are handled under your policy.
Roof Storm Damage Professionals
A roofing contractor can examine the roof, document damage and its likely extent, and describe the repair scope. That written record helps the owner talk with the insurer, but the contractor does not decide coverage. For a complex or disputed claim, some owners also consult a licensed public adjuster or an attorney, and that is a decision for the owner based on the situation.
When to Act
- Active leak or visible membrane damage: protect the contents, document it, and arrange a roof assessment promptly.
- Stains or soft spots without a clear source: arrange an inspection or roof leak detection before assuming the cause.
- Storm passed with no visible damage: a commercial roof inspection in Bismarck can confirm the roof’s condition.
- Before the next storm season: keep dated inspection records. Commercial roof maintenance in Bismarck creates a record of the roof’s condition before any future damage occurs.
To protect your Bismarck, ND commercial building, call Eagle Eye Roofing Systems at (701) 202-7280 to discuss a roof assessment.
Frequently Asked Questions
How quickly should I report storm damage to my insurer?
As soon as you are reasonably able. Policies can set their own reporting deadlines, so check yours or ask your agent. Delays can also allow more damage to occur.
Can an insurer deny a claim based on roof age or existing conditions?
It depends on the policy language and the insurer’s findings. Policies often treat sudden storm damage differently from wear and long-term deterioration, and roof age can affect how a claim is paid.
What is the difference between cosmetic and functional roof damage?
Functional damage affects how well the roof keeps water out, while cosmetic damage affects appearance only. Whether cosmetic damage is covered depends on the policy, so ask your insurer how it treats it.
What should a contractor’s storm damage assessment include?
Dated photos, the location and type of each defect, the likely extent, any moisture findings and their limits, and a written repair scope. It should also say what was not checked.